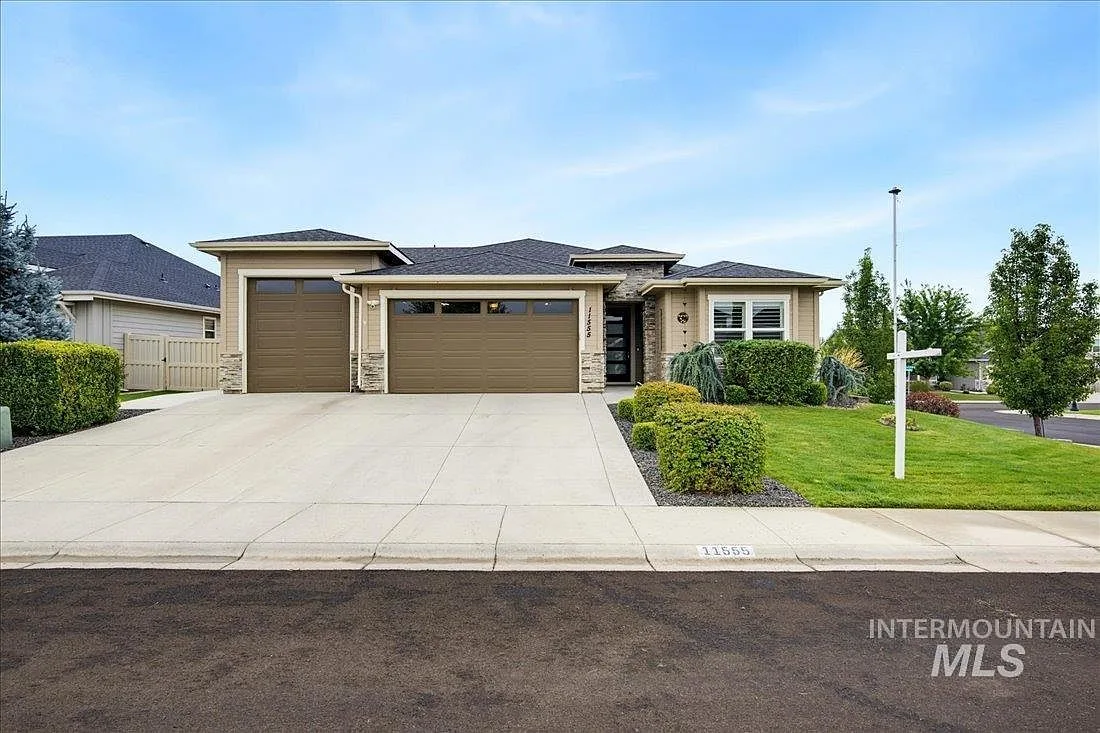
The home at 11555 W Pathview St carries a VA loan that qualified buyers may be able to assume at 2.49%. In a rate environment where new mortgages cost considerably more, that number changes the math. This post explains what loan assumption is, why this rate matters, and what to ask before you rely on it.
What is an assumable mortgage?
An assumable mortgage lets a new buyer take over the seller's existing loan, keeping its interest rate, remaining principal balance, and remaining term instead of originating a new loan at today's rates. Most conventional mortgages are not assumable. VA loans are among the mortgages that can be, subject to lender approval and VA rules.
For the buyer, the appeal is straightforward: the loan's 2.49% rate was locked long ago, and that fixed rate carries forward to you. Over the life of the loan, the difference against a new mortgage at higher rates can be significant.
What assumption actually requires
- Qualification: you still apply with the lender and must meet their credit, income, and debt requirements. Assumption is not automatic.
- The gap: the assumable balance is what remains on the current loan, not the purchase price. You generally make up the difference with your own funds or a second arrangement.
- VA eligibility: VA rules and your eligibility can affect whether and how the assumption works for you. An experienced lender should walk you through it.
- Fees and timing: there are assumption fees and a processing timeline, so factor both into your offer and closing plan.
Questions to ask about this specific loan
When you tour 11555 W Pathview St, bring these questions for the agent and your lender:
- What is the remaining principal balance, and how does it compare with the asking price?
- Do you qualify under the lender's assumption criteria?
- What closing costs and assumption fees apply?
- How long does the assumption approval take, and can you coordinate it with your timeline?
The bottom line
A 2.49% assumable VA loan is one of the strongest financial features of this listing, but it is not a guarantee for every buyer. It rewards preparation: get prequalified, understand the numbers, and ask the right questions early. Paul Knighton can connect you with the details and a lender who knows VA assumption.
The rate on this loan was locked long ago. For a buyer who qualifies, that 2.49% carries forward for the rest of the term.
This post is general information, not financial or legal advice. Verify every number with the lender and your own advisors before making an offer.